Home / Mortgage Broker on the Central Coast
Places I Know · Central Coast NSW
Mortgage broker on the Central Coast: where I started broking
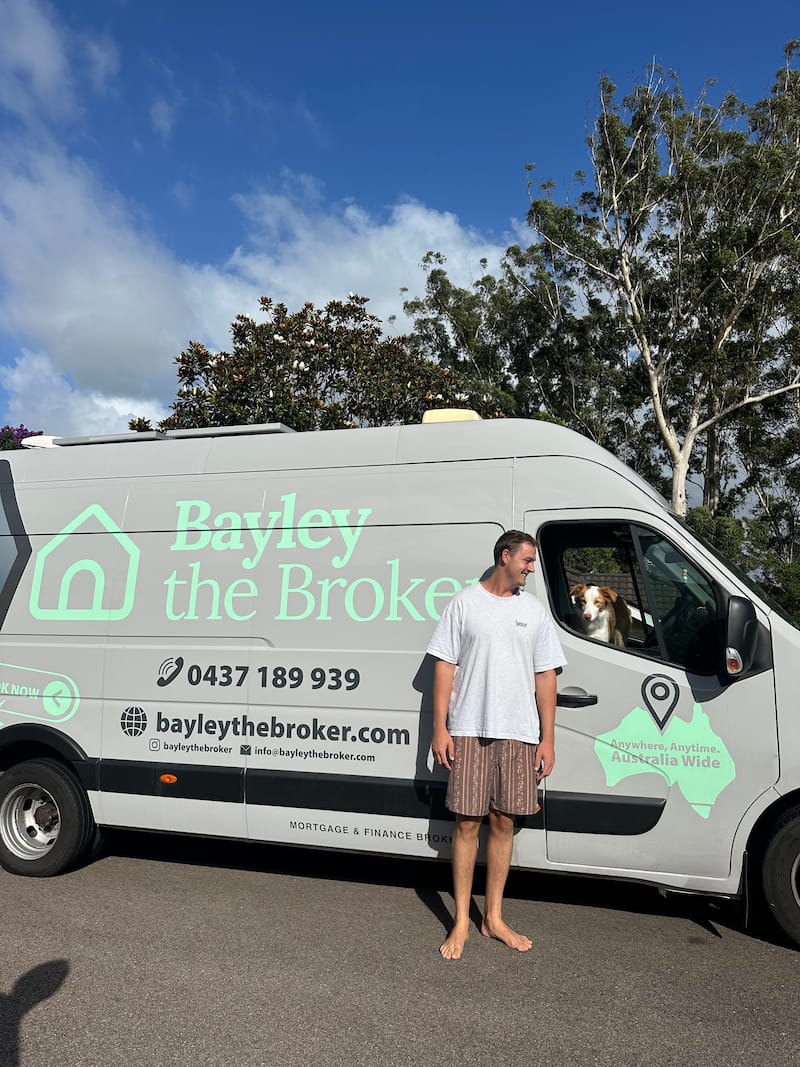 Bayley Clarke · Mortgage broker on the road · Last checked 13 November 2026 · 4 min read
The short answer
If you're on the Central Coast and your bank's number is the only one you've got, you've seen one answer out of a whole panel. Talk me through where your mind's at and I'll tell you straight if I can do better or not.
The Coast is home base. My family's still here, and I started this business in Terrigal in January 2023. More than 15 Coast households have done their loans with me since, from Woy Woy and Umina up to Gorokan and Blue Haven. Phone and video call, wherever the van is. The lender pays me for the work, not you.
We want to buy our first home on the Coast. Where do we start?
Start with the number, not the open homes. How much you can actually borrow decides which suburbs are on the table, and it takes one call to find out. From there it's the deposit, and you may not need as much as you think. Stamp duty and the schemes do a lot of the heavy lifting if you fit the rules, and so can Mum and Dad. One thing to know early: a guarantor and the government 5% scheme do not stack. It's one or the other. And if the first place is a unit and not the forever home, that is normally fine.
I commute, and a big chunk of my pay is overtime and allowances. Does the bank count it?
Depends who you ask, which is the whole point. The bank's going to go, okay, your contract says 38 hours, that's what we count. Another lender counts the overtime and allowances off the same payslips. Some count all of it, some a slice, some want a few payslips first. Casual is the same story, it's time in the job and who we go to. So the same pay can mean two very different borrowing numbers.
We need to sell our place to buy the next one. Which comes first?
Normally you've got three ways to do it. Sell first, buy first, or bridge the gap. You do not always have to sell first, and you can often make an offer before your place has sold. Bridging means you pay a little bit of a premium as a cost of convenience, for the luxury of being able to buy before you've sold. The full guide walks through all three, and which one fits comes down to your numbers.
Same bank since we bought. Are we being taken for a ride?
Maybe. Your bank has no reason to move you. Bring a statement to the call, it takes maybe five, ten minutes to see how you're sitting. If I can beat it, we move, and what a switch costs gets priced before you sign anything. And you know what? If it's not right in the future, I'll move you again.
The bank said no and wouldn't say why. Is that it for us?
No. One no is one lender's policy not fitting. You might like the person at the front counter, but they're only ever going to show you their bank's rules. I don't care which bank we go to, I'm impartial.
The honest bit: sometimes it's not yet, or not me
- If I can't beat what you're on, I'll send you on your merry way. Sometimes the bank you're already with is the right answer.
- I don't have an office on the Coast. It runs by phone, video and email. If you need a desk to sit across from, I'm not that.
- I'm back a few times a year, not every week. Family's here, so the van does come home. If I'm on the Coast when we're working together, we'll grab a coffee. I won't promise it.
- Not yet is different from no. If the deposit or the time in the job isn't there yet, I'll tell you what has to change and when to call me back.
From Central Coast clients
"Bayley has made the process of buying our first house so simple and smooth. Bayley was very easy to contact and was able to answer all our questions when we needed."
"He made what felt like a very daunting and overwhelming refinancing process incredibly easy and completely stress-free."
More reviews, word for word. 5.0 from 120+ on Google.
Want to know how you're sitting?
Book a 30 minute call. It's on the phone, I call you, and it's free for you because the lender pays me, not you. You'll hang up knowing roughly what you could borrow and what's standing in the way. Click the button below and we'll talk soon.
No application, no credit check, nothing on your file. Just the numbers. · How I get paid
Central Coast home loan questions
Do you take on clients on the Central Coast?+
Yes. More than 15 Central Coast households have done their loans with me, from Woy Woy and Umina to Terrigal, Bateau Bay, Killarney Vale and Gorokan. It runs by phone, video and email.
What does a mortgage broker cost on the Central Coast?+
For standard home lending it costs you nothing, because the lender pays me for the work, not you. If your situation ever fell outside that, I'd tell you upfront.
Can we meet face to face?+
Sometimes. My family is on the Coast so I'm back a few times a year, and if the timing lines up we'll grab a coffee. Otherwise it's a phone or video call, which is how most of my Coast loans have been done.
Are you based on the Central Coast?+
I started the business in Terrigal in January 2023. These days I work from a van on the road, and the Coast is where I come back to.
Does a credit card limit count if we clear it every month?+
Yes. Lenders look at the limit, not the balance. Roughly five times the limit comes off your borrowing capacity, so dropping it before you apply normally helps.
Related answers
How much can I actually borrow? What is the first step to buy your first home? Do first home buyers still pay stamp duty? Should I pay LMI or keep saving for 20%? Do shift allowances and penalties count as income? Do I have to sell my current home before I buy the next one? Does my credit card limit affect my borrowing power? Bank valuation or agent appraisal: which one counts? Do I pay you? How does a mortgage broker get paid, and what's the catch?The full guides
How to buy your first home: every pathway explained Buying your next home: sell first, buy first, or bridge Refinancing your home loan with a brokerNot your question? Book a call and ask it, or call 0437 189 939.