Home / Mortgage Broker on the Gold Coast
Places I Know · Gold Coast QLD
Mortgage broker on the Gold Coast: no office, straight answers
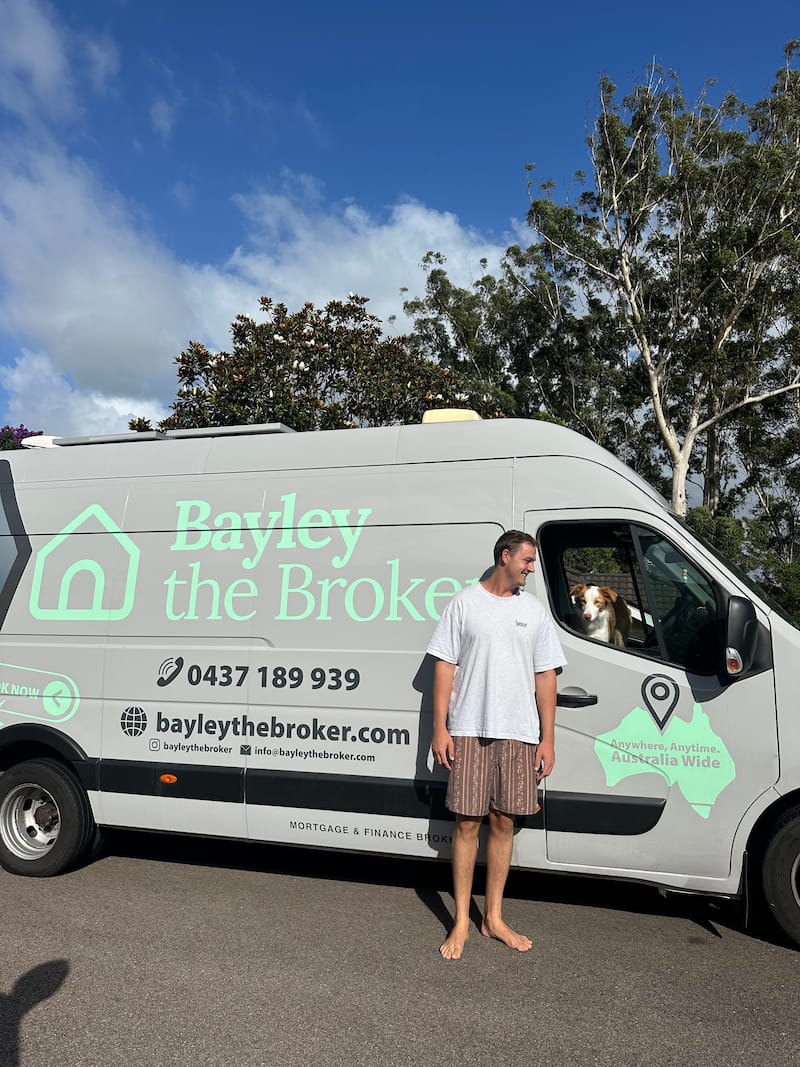 Bayley Clarke · Mortgage broker on the road · Last checked 13 November 2026 · 4 min read
The short answer
If you're on the Gold Coast and your bank's number is the only one you've got, you've seen one answer out of a whole panel. Talk me through where your mind's at and I'll tell you straight if I can do better or not.
Straight up: I don't have an office on the Gold Coast, even if Google sometimes shows me like I do. I work from a van, by phone and video call. Eight Gold Coast households have done their loans with me so far, from Surfers Paradise and Biggera Waters out to Nerang and Mudgeeraba. The lender pays me for the work, not you.
Will the bank lend on a unit or a high-rise apartment?
Normally yes, but this is where the Gold Coast catches people out. Some lenders are fussy about very small apartments, usually set by the internal floor area, and about buildings or postcodes with a lot of the same stock. That can mean a bigger deposit or fewer lenders, not a no. So send me the listing before you make an offer, because it's a lot easier to know which lenders will touch a building before you're attached to it. And the number that matters is the bank's valuation, not the agent's price guide.
We want to buy our first home here. Where do we start?
Start with the number. How much you can actually borrow decides whether you're looking at a house out west or a unit closer to the beach, and it takes one call to find out. Stamp duty and the schemes work differently state to state, so the Queensland rules are the ones we check. And if the first place is a unit and not the forever home, that is normally fine. The idea is that you start.
Should we buy an investment property before our own home?
It can work, and it has a name now, rentvesting. The catch is what it does to your first home buyer benefits, so that gets checked before you sign, not after. If you already own a place and want to use it to buy the next one, equity is not the same thing as borrowing power. It's all an income versus expense conversation. The investment guide has the detail.
Same bank since we bought. Are we being taken for a ride?
Maybe. Your bank has no reason to move you. Bring a statement to the call, it takes maybe five, ten minutes to see how you're sitting. If I can beat it, we move. And you know what? If it's not right in the future, I'll move you again.
I'm self-employed. Will the bank read my numbers the way my accountant does?
Normally not. Your accountant's job is to keep your taxable profit down, and the bank's job is to find the income. Which years they read and what they add back changes lender to lender, so who we go to matters as much as what's on the return. The self-employed guide covers how they read it.
The honest bit: sometimes it's not yet, or not me
- If I can't beat what you're on, I'll send you on your merry way. Sometimes the bank you're already with is the right answer.
- No office, no shopfront. If you want to sit across a desk from someone in Southport or Robina, I'm not that. It runs by phone, video and email.
- Some buildings. A few apartment types narrow the lender list fast. You'll hear that in the first ten minutes, not after three weeks of paperwork.
- Not yet is different from no. If the deposit or the time in the job isn't there yet, I'll tell you what has to change and when to call me back.
From Gold Coast clients
"We originally contacted him on a Sunday because we needed help urgently, and he was there for us straight away. Bayley explained everything clearly, stayed in touch, and was always available when we had questions."
"Bayley is always in a good mood, very responsive and helped us to navigate through the jungle of things to know when buying a property. Very much appreciated!"
More reviews, word for word. 5.0 from 120+ on Google.
Want to know how you're sitting?
Book a 30 minute call. It's on the phone, I call you, and it's free for you because the lender pays me, not you. You'll hang up knowing roughly what you could borrow and what's standing in the way. Click the button below and we'll talk soon.
No application, no credit check, nothing on your file. Just the numbers. · How I get paid
Gold Coast home loan questions
Do you have an office on the Gold Coast?+
No. I work from a van on the road, by phone, video and email. Eight Gold Coast households have done their loans with me that way so far.
What does a mortgage broker cost on the Gold Coast?+
For standard home lending it costs you nothing, because the lender pays me for the work, not you. If your situation ever fell outside that, I'd tell you upfront.
Can we meet face to face?+
Usually not. If the van happens to be on the Gold Coast we can grab a coffee, but plan on a phone or video call.
Will a bank lend on a small apartment in Surfers Paradise?+
Often, but not every lender. Some set a minimum internal floor area and some are cautious about buildings with a lot of the same stock, which can mean a bigger deposit or a shorter lender list. Send the listing before you make an offer.
Does a credit card limit count if we clear it every month?+
Yes. Lenders look at the limit, not the balance. Roughly five times the limit comes off your borrowing capacity, so dropping it before you apply normally helps.
Related answers
How much can I actually borrow? Can my first home be something cheaper, like a unit, instead of holding out for my forever home? Bank valuation or agent appraisal: which one counts? Rentvesting: buy the investment first and keep renting. Does it work? Why doesn’t my equity count as borrowing power? Do first home buyers still pay stamp duty? What does refinancing actually cost? You're recommending a bank I've never heard of. Is it safe? Do I pay you? How does a mortgage broker get paid, and what's the catch?The full guides
Investment property loans: how the bank sees your purchase Which properties banks won't lend on, and why Self-employed home loans: how the bank reads your financialsNot your question? Book a call and ask it, or call 0437 189 939.