Home / Mortgage Broker in Glen Innes
Towns I Know · New England
Mortgage broker in Glen Innes, the town where I became a broker
 Bayley Clarke · Mortgage broker on the road · Updated 6 September 2026 · 5 min read
The short answer
Glen Innes is where my broking career grew up. I lived there when I started out, and I still look after locals there today.
First home, refinance, investment, and the smaller loans plenty of the industry won't fight for. For standard home lending it costs you nothing, because I get to charge the bank for the work that I do, not you.
I'd never heard of Glen Innes when I applied for a rental there
When I was starting out as a broker, I was living in Terrigal on the Central Coast and needed somewhere cheaper to live. So I fired off rental applications all over regional NSW and took the first place that said yes: a two-bedroom unit in Glen Innes, a kilometre above sea level, in a town I had to look up on a map.
Nine months there, through a winter that redefined what I thought cold meant. And it turned out to be the best accident of my working life. Glen Innes is where my broking career grew up. It's where I learned that country lending has its own rules, and that in a small town your name is the only marketing that matters. Glen Innes families have done their loans with me since, and the town that took a punt on my rental application ended up shaping how I work with every client I have.
Nobody fights for the small loans
Here's the uncomfortable truth about towns like Glen Innes: because you can still buy a solid home there without a city-sized mortgage, the loans are smaller, and plenty of the lending industry quietly loses interest. Some lenders have minimum loan amounts. Some offers exclude smaller loans altogether. And some brokers won't return calls when the numbers aren't big enough to be worth their while.
I built my book on exactly those loans. A $300k mortgage in Glen Innes is not a small thing. It's someone's whole life sitting on a contract. It gets the same lender comparison, the same negotiation, and the same follow-up as a million-dollar mortgage in Sydney. That's not a slogan. It's just where I come from.
What country properties taught me about banks
Glen Innes housing is full of character: older weatherboard and brick homes, generous blocks, the odd few acres on the edge of town. Banks, it turns out, have opinions about all of that.
Some lenders get twitchy about property age and condition. Some cap how much land they'll accept before they reclassify the deal. Some just aren't set up to value homes in certain postcodes, and their valuation comes back conservative, whatever the agent told you it was worth. The same house, the same income, the same deposit can get a genuinely different answer depending on which lender you ask.
So for you, that means the choice of lender matters more in the country than it does in the city. The order you approach them in is half the job. That's the half I do. I don't care which bank we end up at, I'm impartial: you get the answer that fits your property, not the answer of whichever bank still has a branch nearby.
What I help Glen Innes locals with
- First home buyers: Glen Innes is one of the few places left where a first home is genuinely within reach on a normal income. Borrowing power, stamp duty and the schemes that may apply, and guarantor options if family want to help. Every pathway is laid out in the first home guide
- Refinancing: if your loan has been sitting untouched for a couple of years, it's normally worth a review. Loyalty rarely gets rewarded by a bank
- Upgrading, building or renovating: selling and buying, construction loans, turning the character home into the finished one
- Investment: regional yields draw investors from everywhere; structure it properly from the start
- Farm, family business or self-employed income: the payslip isn't the number the bank uses, and working for family gets read differently again. How lenders read your financials is in the self-employed guide
How it works when your broker lives in a van
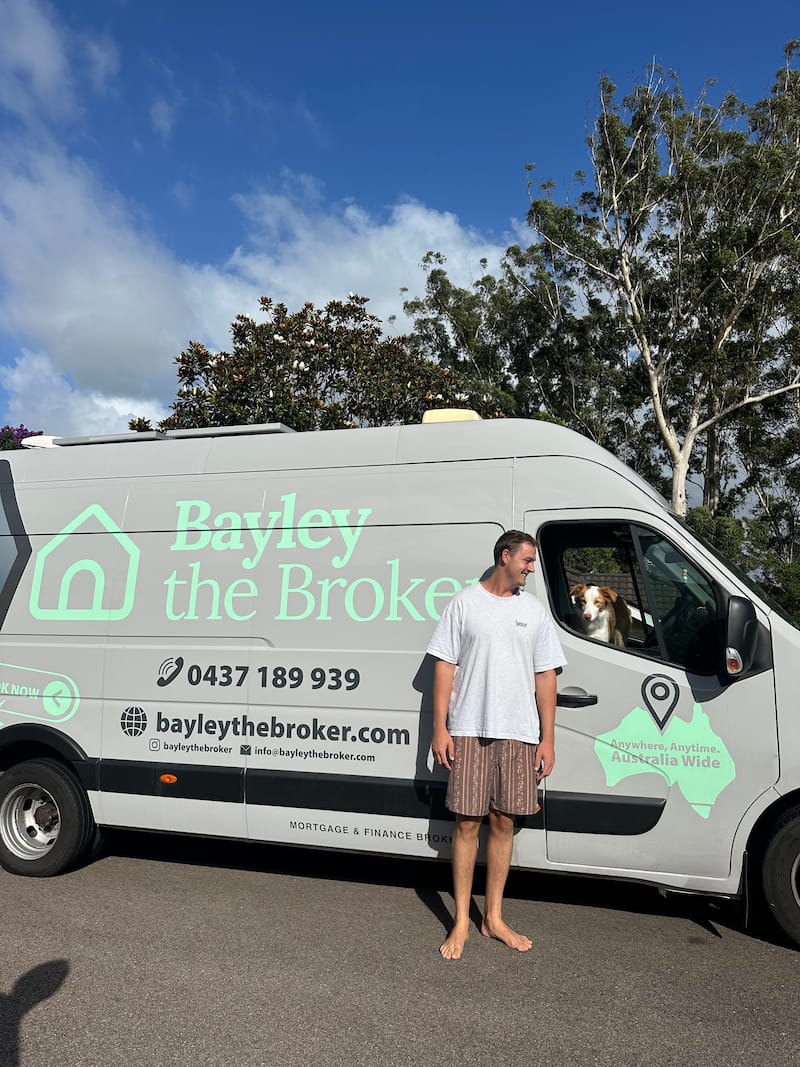
No office. No suit. I run my whole business from the road: phone, video, and email. The same way I look after clients everywhere, from the next town over in Inverell to the other side of the country. You don't book an appointment in a branch three weeks out. You grab 15 minutes with me between school pickup and dinner.
And the bit people take a while to believe: for standard home lending, my work costs you nothing. I get to charge the bank for the work that I do, not you. That's true whether your loan is $250k or $2.5M. It's the reason my 110+ Google reviews read the way they do.
If you're in Glen Innes (or Deepwater, Emmaville, Glencoe, Red Range, anywhere along the highlands) and you're wondering what's possible for you, give me a call. There's a fair chance I used to walk past your street on the way to get coffee.
Wondering what's possible for you?
A 15-minute chat is enough to work out your borrowing power and your next step, even if that step is "save for another six months". Costs you nothing, and you'll know exactly where you stand.
No application, no credit check, nothing on your file. Just the numbers.
Glen Innes home loan questions
Do you still work with clients in Glen Innes?+
Yes. I don't live in Glen Innes anymore, but it's where my broking career started and I still look after locals there. Everything runs over phone and video, so being in town isn't a requirement. And the van does roll back through the New England from time to time.
What does a mortgage broker cost in Glen Innes?+
For standard home lending, nothing. The lender pays me a commission when your loan settles. I get to charge the bank for the work that I do, not you. If your situation ever fell outside that, I'd tell you upfront before anything started.
My loan would only be around $250k to $350k. Will anyone take it seriously?+
I will. Smaller regional loans are exactly where I started, and they deserve the same work as a million-dollar city mortgage. Some lenders also have minimum loan amounts or offers that exclude smaller loans. Which is exactly why it pays to have someone compare properly rather than walking into the nearest branch.
I'm a first home buyer in Glen Innes. Where do I start?+
A 15-minute chat. Glen Innes is one of the few places left where a first home is genuinely within reach on a normal income. We work out your borrowing power, whether any government schemes may apply, and whether a guarantor could get you in sooner. You'll leave the call knowing your next step.
The place I want is older, or on acreage. Is that a problem for the bank?+
It can change which lender is the right fit. A lot of Glen Innes housing is older weatherboard or brick on generous blocks, and some lenders are pickier than others about property age, condition, land size, and postcode. It rarely means no. It means the choice of lender matters more out here, and the order you approach them in is half the job.
Related answers
How much can I actually borrow? How does a guarantor home loan actually work? Guarantor loan or the government 5% scheme: which one is best? Do first home buyers still pay stamp duty? Can I buy a block of land now and worry about the build later? Why won’t banks finance tiny homes? Bank valuation or agent appraisal: which one counts? Will the bank give me a home loan if I'm casual? I'm self-employed. How many years of financials do I need, and which ones count? Broker or going direct to the bank: which gets me the best deal? Do I pay you? How does a mortgage broker get paid, and what's the catch?The full guides
How to buy your first home: every pathway explained Why did the bank say no to my home loan? Self-employed home loans: how the bank reads your financialsGot a question this page didn't answer? Send it to me and it goes on the list.